Kitchen
Kitchen Remodel Financing: HELOC vs Home Equity vs Refi
Kitchen remodel financing with home equity: how a HELOC, a home equity loan and a cash-out refinance compare, and which fits your project.
By the Prime Construction team Updated October 13, 2026 5 min read
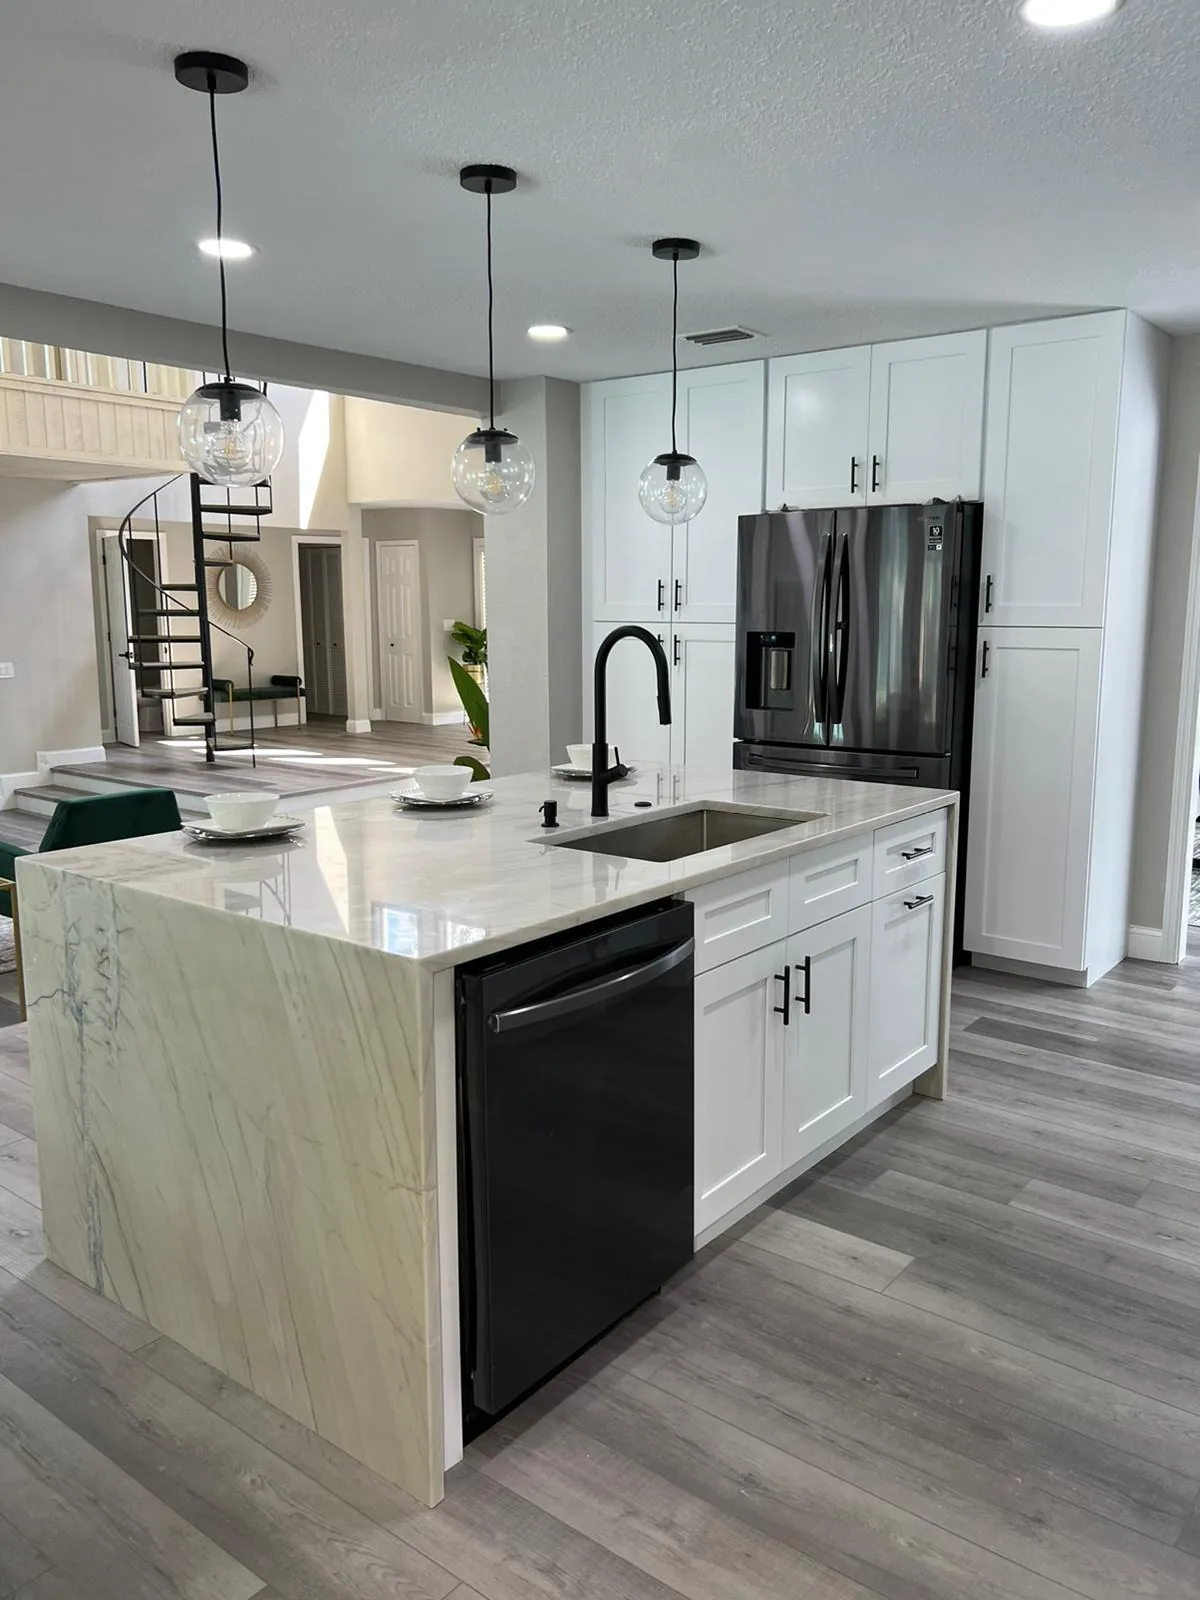
For most homeowners with equity, kitchen remodel financing comes down to three options: a home equity line of credit (HELOC), a home equity loan, or a cash-out refinance. A HELOC lets you draw money as the work progresses, a home equity loan gives you one lump sum with fixed payments, and a cash-out refinance replaces your mortgage with a larger one. All three are secured by your house, which is why they usually cost less than unsecured borrowing, and why you should borrow carefully.
This post focuses only on home equity. For the full list of options (personal loans, cards, renovation mortgages), see our overview of kitchen remodel financing options.
What home equity is and how lenders use it
Home equity is your home’s current value minus what you owe on it. Lenders typically appraise or value the home, subtract your mortgage balance, and then apply their own limit on how much of the value they will lend against in total. Each lender sets its own limits and requirements, so two lenders can offer different maximums on the same house.
Two practical points:
- Your kitchen estimate sets the amount, not the maximum approval. Being approved for more than you need is not a reason to borrow it.
- The house is the collateral. If you cannot make the payments, you can lose the home. Keep the payment comfortable even if your income drops for a while.
HELOC vs home equity loan vs cash-out refinance
| Feature | HELOC | Home equity loan | Cash-out refinance |
|---|---|---|---|
| How you receive money | Draw as needed during a draw period | One lump sum at closing | Lump sum at closing |
| Your first mortgage | Stays as is | Stays as is | Replaced by a new, larger mortgage |
| Payment | Often variable; may be interest-only during the draw period | Usually fixed | Depends on the new mortgage |
| Best fit | Phased projects, uncertain final cost | One project with a firm price | When refinancing helps your mortgage anyway |
| Closing costs | Often lower, varies by lender | Varies by lender | Usually the highest of the three |
| Main risk | Payment can rise; temptation to overdraw | Interest on the full amount from day one | Resets your mortgage; higher closing costs |
No rates or terms are listed because they change and depend on your credit, income and home. Get every offer in writing.
When a HELOC fits a kitchen remodel
A HELOC works like a credit line secured by your house. It fits kitchens well because remodel costs come due in stages: a deposit at ordering, payments at cabinet delivery and installation, and a final payment after the walk-through.
A HELOC makes sense when:
- You want to pay each invoice as it comes rather than borrow everything at once.
- The scope may grow (for example, you might add a pantry wall or upgrade appliances once you see the rendering).
- You plan more work later, such as a bathroom next year.
What to ask the lender:
- Is the rate variable, and how is it calculated?
- How long is the draw period, and what happens to the payment when it ends?
- Are there annual fees, minimum draws or early closure fees?
When a home equity loan fits
A home equity loan gives you the full amount at closing with a fixed repayment schedule. It fits when:
- You have a signed contract with a firm price, such as a mid-range full remodel.
- You value a predictable payment over flexibility.
- You do not want an open credit line you might be tempted to use for other things.
The drawback: you pay interest on the whole amount from the day it funds, even if the contractor will not need the final payment for weeks. Keep the funds in a separate account so they are not spent on anything else.
When a cash-out refinance fits
A cash-out refinance pays off your current mortgage with a new, larger one, and you receive the difference. It can make sense if:
- Refinancing improves your mortgage anyway, for example a better term or terms than you have now.
- You need a larger amount for a high-end kitchen or whole-home project.
- You prefer one housing payment instead of a mortgage plus a second loan.
If your current mortgage terms are better than what is available today, a cash-out refinance can make all of your mortgage debt more expensive just to fund the kitchen. In that case a HELOC or home equity loan usually costs less overall. In Florida, closing costs on a new recorded mortgage include state documentary stamp tax and intangible tax, so ask for a full closing cost estimate.
Match the loan to the kitchen scope
Typical Orlando-area planning ranges for 2026, installed:
- Cosmetic refresh, same layout: $15,000 to $35,000. Often a fit for a HELOC, a smaller home equity loan, or savings plus a small loan.
- Mid-range full remodel: $35,000 to $75,000. Home equity loans and HELOCs are both common.
- High-end or layout change: $75,000 to $150,000+. HELOC or home equity loan if equity allows; cash-out refinance if refinancing makes sense anyway.
Your number comes from a written estimate after measuring. See our Orlando kitchen remodel cost guide for what drives each tier, and add a 10 to 15 percent contingency before you apply.
Timing the loan with the remodel
Home equity loans take weeks, not days. A typical sequence:
- Measure and design. Get the in-home measure, 3D rendering and selections done. This is when you learn the real price.
- Apply while design is finishing. Bring the written estimate. The appraisal and title work can run in parallel with selections.
- Close before cabinets are ordered. The ordering deposit is often the first large payment, and cabinet lead times drive the schedule.
- Draw or pay on the contractor’s schedule. On-site work for a full kitchen remodel typically takes 4 to 8 weeks.
Taxes and home equity
Federal tax rules can allow a deduction for interest on home equity debt used to buy, build or substantially improve the home that secures it, within limits. Those rules have changed over the years, and whether it helps depends on whether you itemize. Read IRS Publication 936 and ask a tax professional before counting on a deduction.
Where Prime Construction fits
Prime Construction does not offer financing and does not arrange loans. We provide what home equity lenders commonly ask for: a detailed written scope and estimate after we measure, a 3D rendering that pins down the scope, our license information, and a payment schedule you can match to your draws. If you would rather borrow less, we can phase the project.
Planning a kitchen remodel in Orlando?
Before you apply for a HELOC or home equity loan, get a measured estimate so you borrow the right amount. Prime Construction handles kitchen remodeling across Orlando and nearby communities such as Windermere and Oviedo. Call (407) 404-3944 or request an estimate.