Bathroom
How to Finance a Bathroom Remodel: Options Compared
How to finance a bathroom remodel: savings, HELOC, home equity loan, personal loan, cash-out refi, cards and renovation loans compared side by side.
By the Prime Construction team Updated October 13, 2026 6 min read
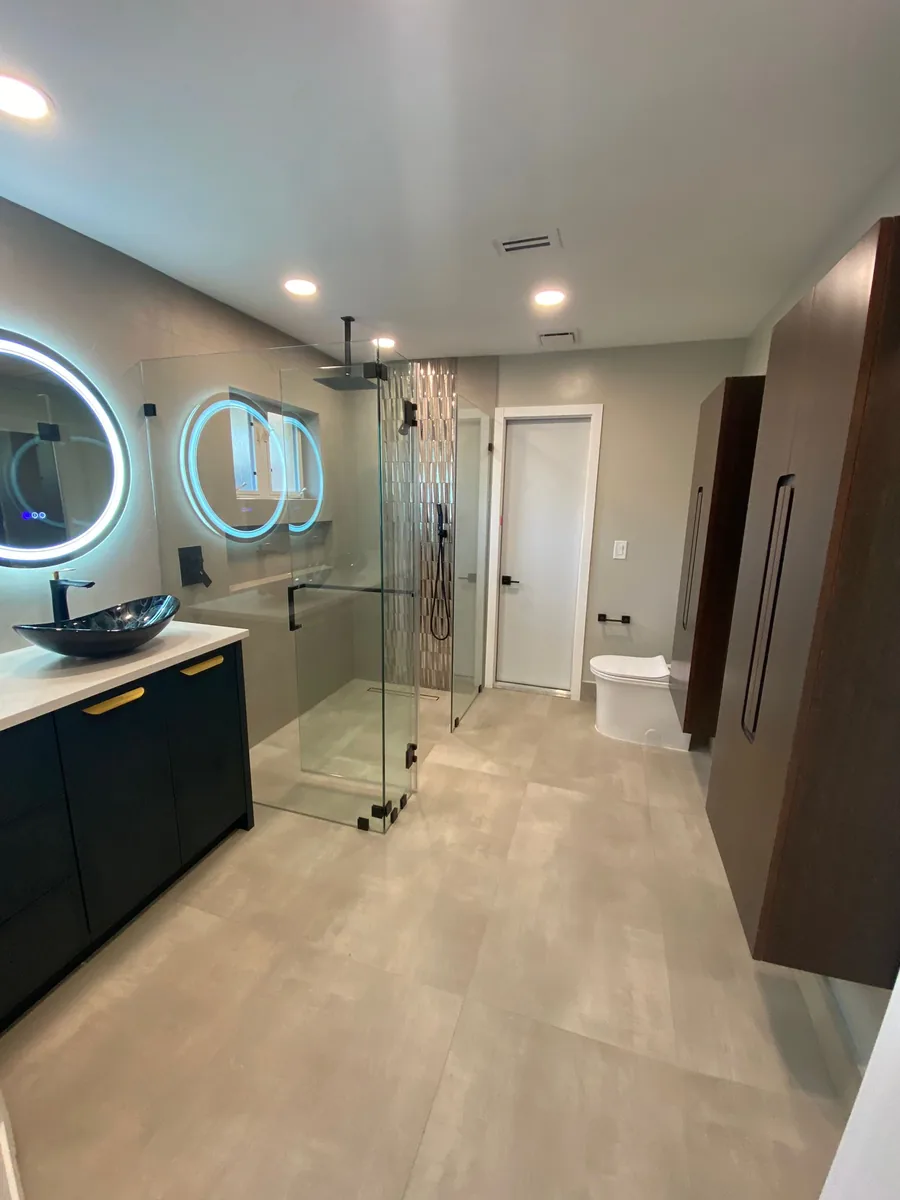
To finance a bathroom remodel, most homeowners choose between savings, a home equity line of credit (HELOC), a home equity loan, an unsecured personal loan, a cash-out refinance, a credit card or promotional account, or a government-backed renovation loan. The best option depends on project size, how much equity you have, how quickly you can repay, and how soon the work has to start. The table below compares them side by side so you can narrow the list before you talk to a lender.
If you want the Orlando-specific overview instead (permits, phasing, what local lenders ask a contractor for), see our Orlando bathroom remodel financing guide.
Bathroom remodel financing options side by side
| Option | Secured by your home? | How you get the money | Speed | Best fit | Main drawback |
|---|---|---|---|---|---|
| Cash or savings | No | You pay as you go | Immediate | Any size, if saved | Uses your emergency reserve |
| HELOC | Yes | Draw as needed during a draw period | Weeks (appraisal, title) | Larger or phased remodels | Payments can change; home is collateral |
| Home equity loan | Yes | One lump sum, fixed payments | Weeks | One large, fixed-price project | Pay interest on the full amount from day one |
| Cash-out refinance | Yes | Replaces your mortgage with a larger one | Weeks to over a month | Owners who also want to change their mortgage | Resets the mortgage; closing costs |
| Personal loan | No | Lump sum, fixed payments | Days | Guest baths, powder rooms, urgent repairs | Usually costs more than secured borrowing |
| Credit card or promo account | No | Revolving balance | Immediate | Fixtures, vanities, small repairs | Expensive if not paid off; deferred-interest traps |
| FHA 203(k) or conventional renovation mortgage | Yes | Rolled into a purchase or refinance; funds released in stages | Longest | Buying a home that needs work | Most paperwork and lender rules |
| FHA Title I property improvement loan | Only larger loans (HUD requires security above $7,500) | Through an approved lender | Varies | Owners with limited equity | Must find a lender that offers it; amounts are capped |
No lender’s terms are listed here because they change constantly and depend on your credit, income and home. Lenders set their own requirements; always get the full terms in writing.
Know your project cost before you compare
Every row in that table works better when you know what you are borrowing for. Typical Orlando-area 2026 planning ranges, installed:
- Powder room: $5,000 to $12,000
- Same-layout guest or hall bath (about 5x8): $12,000 to $25,000
- Full primary bathroom: $25,000 to $50,000
- Luxury primary or layout change: $50,000 to $90,000+
A written estimate after measuring is the real number. Line-item detail, room by room, is in our guide to estimated bathroom remodeling costs.
Option by option: when each one makes sense
Savings
Best when you can afford it without emptying your reserve. A practical approach is to save for a set period while the design is finalized and materials are selected; bathroom design and ordering takes 2 to 6 weeks anyway. If you are short, combine savings with a smaller loan rather than financing the whole job.
HELOC
A HELOC works like a credit line secured by your home. You draw money as invoices come due and generally pay interest only on what you have drawn. That makes it a good match for a bathroom project paid in stages, or for doing one bathroom now and another later. Ask whether the payment can change over time and what happens when the draw period ends.
Home equity loan
You get the full amount at closing and repay it on a fixed schedule. This suits a single project with a firm contract price, such as a full primary bathroom remodel. Because you receive the money at once, interest starts on the whole balance immediately.
Cash-out refinance
You replace your current mortgage with a larger one and take the difference in cash. It can make sense if refinancing improves your mortgage anyway. If your existing mortgage terms are better than what is available now, a separate HELOC or home equity loan usually leaves that mortgage alone.
Personal loan
Unsecured, fast and simple. Many personal loans fund within days of approval, which helps with a leaking shower or a tub-to-shower conversion that cannot wait. Loan amounts and terms are more limited, and the cost is usually higher than borrowing against your home.
Credit cards and promotional plans
Useful for a vanity, faucet or a small repair you can pay off in a few months. Offers like “no interest if paid in full” are usually deferred interest. On many of these, if a balance remains when the promotional period ends, interest is charged back to the purchase date. Mark the end date and divide the balance by the number of months left.
Government-backed renovation loans
FHA 203(k) loans let a buyer or refinancing owner roll repair and renovation costs into an FHA-insured mortgage. Conventional renovation mortgages work in a similar way. FHA Title I loans are a separate HUD program for property improvements made through approved lenders. These programs have rules about eligible work, contractor documentation and inspections, and they take longer. HUD explains the 203(k) program and the Title I program on its site; ask an approved lender whether your bathroom project qualifies.
Our kitchen renovation loan guide explains these programs in more depth. The same rules apply to bathrooms.
Five questions to ask every lender
- What is the total cost over the life of the loan, including fees and closing costs?
- Is the payment fixed, or can it change?
- Is there a penalty for paying it off early?
- How and when are funds released: lump sum, draws, or direct payment to the contractor?
- What documents do you need from the contractor, and by when?
Comparing answers to these five questions tells you more than comparing advertised monthly payments.
Mistakes that make bathroom financing more expensive
- Borrowing before the scope is final. Changes after the loan closes often go on a credit card.
- Skipping the contingency. Bathrooms hide problems: rotted subfloor, failed shower pans, old supply lines. Add 10 to 15 percent to the estimate.
- Choosing by monthly payment only. A longer term can feel cheaper while costing much more overall.
- Letting a promo period run out. Deferred interest can wipe out the savings you expected.
- Paying a large deposit before permits are pulled. In Florida, a contractor who takes more than 10 percent of the contract price up front must apply for permits within 30 days and start work within 90 days after the permit is issued, unless the contract provides otherwise as the law allows.
Where your contractor fits in
A contractor is not a lender, and Prime Construction does not offer financing. What we provide is what lenders ask for: a detailed written scope and estimate after we measure, our license information (Certified General Contractor CGC1535686 and Certified Plumbing Contractor CFC1433952), and a clear payment schedule tied to the work. If the full remodel does not fit the budget now, we can phase it, for example a new walk-in shower first and the vanity and floor later.
Planning a bathroom remodel in Central Florida?
Before you compare loans, get a real scope and price for the room. Prime Construction measures your bathroom, prepares a detailed written estimate you can take to any lender, and can phase the work to match your budget. Learn about our bathroom remodeling in Orange, Seminole, Osceola and Lake counties, call (407) 404-3944, or request an estimate.